Another interest rate rise can be frustrating, especially when your home loan is already taking up a significant part of your household budget.
The question for many Australians isn’t necessarily why rates have gone up again. It’s what they can do about it.
On Tuesday 3 November 2026, the Reserve Bank of Australia (RBA) raised the cash rate by 0.25 percentage points, taking it to 4.85%. The RBA cash rate influences home loan interest rates, but individual lenders decide when and how much to change their rates.
An RBA rate rise is a good opportunity to check where you stand. Understanding your repayments, reviewing your budget, comparing your current home loan and knowing what support is available can help you make informed decisions. You don’t need to change everything at once. Here are six places to start.
1. Check what your lender is actually changing
Your home loan interest rate won’t necessarily increase by the same amount as the RBA rate rise.
Still, if you have a variable-rate home loan, your lender may announce a new rate and the date it takes effect. Your repayment amount might also change, depending on your loan terms.
A few things worth checking are:
- Your current interest rate and any new rate announced
- When the change takes effect
- When your next repayment is due and how much it will be
If your loan has a fixed interest rate, the rate generally stays unchanged until your fixed period ends. For split loans, the variable portion may be affected.
Knowing your new repayment amount makes it easier to plan ahead.
Your lender’s updated repayment notice is the most useful place to confirm the amount. A home loan repayment calculator can also help you explore different scenarios.
It can be useful to consider not only the next repayment, but how the change affects your finances over several months. That gives you a clearer picture of how much flexibility remains in your budget.
2. Give your household budget another look
A rate rise is a useful reminder to review where your money is going.
Finance broker, Ly Nguyen, suggests “looking at your monthly living expenses and compar[ing] your needs and your wants.”
Start with the essentials: housing, groceries, utilities, transport, insurance and existing debt repayments. Then look at expenses that might have more flexibility, such as unused subscriptions or services that haven’t been reviewed recently.
Here’s a simple example of how a change in repayments can affect the amount left over each month.
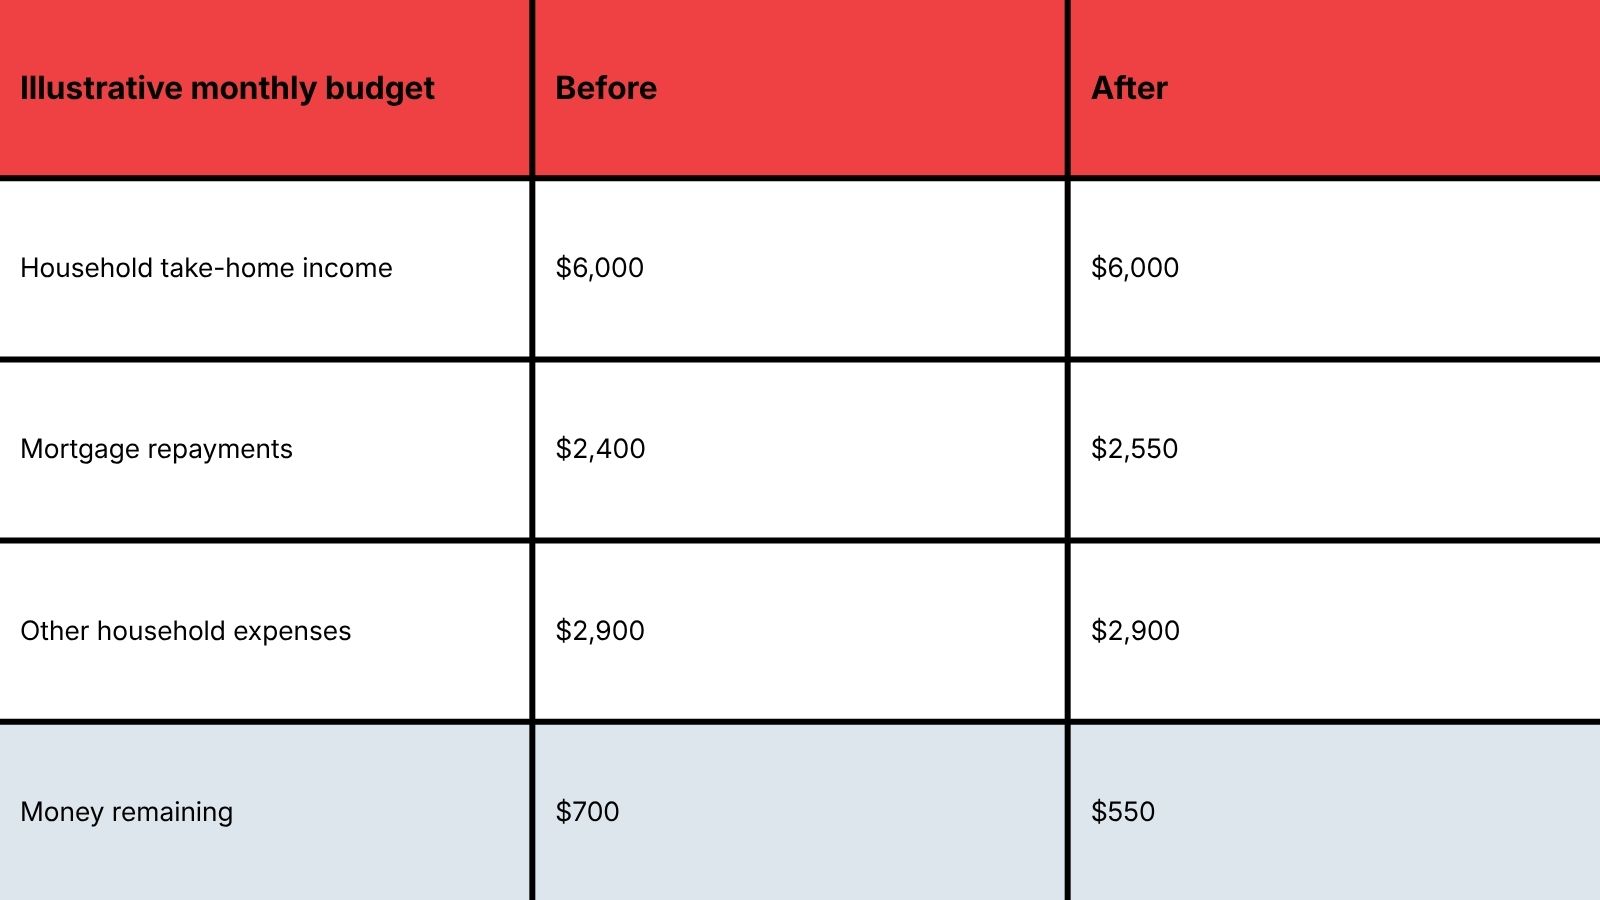
This example uses a hypothetical $150 monthly repayment increase, not a calculation of the announced rate rise.
“I know there’s a lot of temptations out there,” Ly says. Her advice is not to cut all non-essentials, but she stresses that putting the money you save aside to build an emergency cash buffer will help you withstand future rate changes.
A budget planner calculator can help you understand what is affordable now, and where there may be room to adjust.
3. Ask your current lender if a better rate is available
Just because interest rates have increased doesn’t mean every borrower is paying the same rate.
Lenders offer different rates based on the loan, borrower circumstances and other factors. Existing borrowers may also be paying a different rate from someone taking out a similar loan today.
“I think there’s always an opportunity to review your existing lending [when rates rise]” Finance Broker, Mars Hana says.
One practical step is to contact your lender and ask for a home loan rate review.
You could ask:
- Is my current rate competitive with your other available offers?
- Are there any discounts available on my existing loan?
- Would changing my loan package affect my fees or features?
There’s no guarantee your lender will offer a lower rate, but asking can help you understand your position before considering other options.
4. Consider whether refinancing is worth exploring
If your current home loan no longer feels competitive, it may be worth comparing what’s available elsewhere.
Refinancing means replacing your existing home loan with another loan, either with your current lender or a different one. Depending on the circumstances, it could provide access to a different interest rate, repayment structure or loan features.
But a lower advertised rate doesn’t automatically mean a better overall outcome.
As ASIC’s Moneysmart explains, switching loans can involve application fees, discharge costs, potential break fees and other expenses. Extending your loan term might also lower repayments now while increasing the total interest paid.
Loan features matter too. For example, offset accounts and redraw facilities can offer different benefits and limitations. Our article on the difference between offset and redraw explains why this deserves attention.
5. Recheck your numbers if you’re planning to buy property
For Australians preparing to buy their first home, upgrade or purchase an investment property, an RBA rate rise is another reason to revisit the numbers.
Higher home loan interest rates can affect borrowing capacity, which is the amount a lender may be prepared to lend based on income, expenses and other financial commitments.
If you received a borrowing estimate or pre-approval before the rate change, it may be worth confirming whether your position has changed.
There are two different numbers to think about: what a lender may approve and what repayments feel comfortable within your own budget.
Understanding both can help you approach property decisions with more clarity, without feeling pressured to rush.
6. Know what support is available if repayments are becoming difficult
Sometimes a rate rise is manageable with a few changes. Other times, it can put additional pressure on an already tight budget.
If meeting mortgage repayments is becoming difficult, there are options worth discussing before payments are missed.
“As long as you’re prepared or willing to sit down and talk about your circumstances and come up with a strategy, I think there’s a possibility to help everyone in almost every situation,” Mars says.
UFinancial’s Finance Advisers can review your loan to give you clarity about potential savings areas, compare lending options and work through the potential costs and benefits of making a change.
Asking for help early can provide more time to understand your options. You don’t have to have everything worked out before starting that conversation.
Explore our home loan refinancing service or have a conversation with the team about where things stand.
Book a chat or call 1800 835 626.
Frequently asked questions about the RBA rate rise
Can I refinance my home loan if I’m on a fixed interest rate?
Refinancing during a fixed-rate period may be possible, but breaking the existing loan could involve additional costs. These can sometimes be substantial. It is worth understanding any break fees, the remaining fixed period and the total cost of switching before comparing alternatives.
Can an offset account help when interest rates rise?
An eligible offset account can reduce the loan balance on which interest is calculated, potentially reducing interest costs. It doesn’t prevent the lender from increasing your rate. The benefit depends on your offset balance, loan structure and account conditions, including any fees that apply.
Does an RBA interest rate rise affect investment property loans?
It can. If an investment property has a variable-rate loan and the lender increases its rate, borrowing costs may rise. Investors may want to review repayments alongside rental income, property expenses and available cash flow. Any tax implications depend on individual circumstances and should be discussed with a registered tax professional.
Disclaimer: The content of this article is general in nature and is presented for informative purposes. It is not intended to constitute tax or financial advice, whether general or personal nor is it intended to imply any recommendation or opinion about a financial product. It does not take into consideration your personal situation and may not be relevant to circumstances. Before taking any action, consider your own particular circumstances and seek professional advice. This content is protected by copyright laws and various other intellectual property laws. It is not to be modified, reproduced, or republished without prior written consent.
UFinancial Planning representatives are authorised by Consultum Financial Advisers Pty Ltd, ABN 65 006 373 995, AFSL 230323.