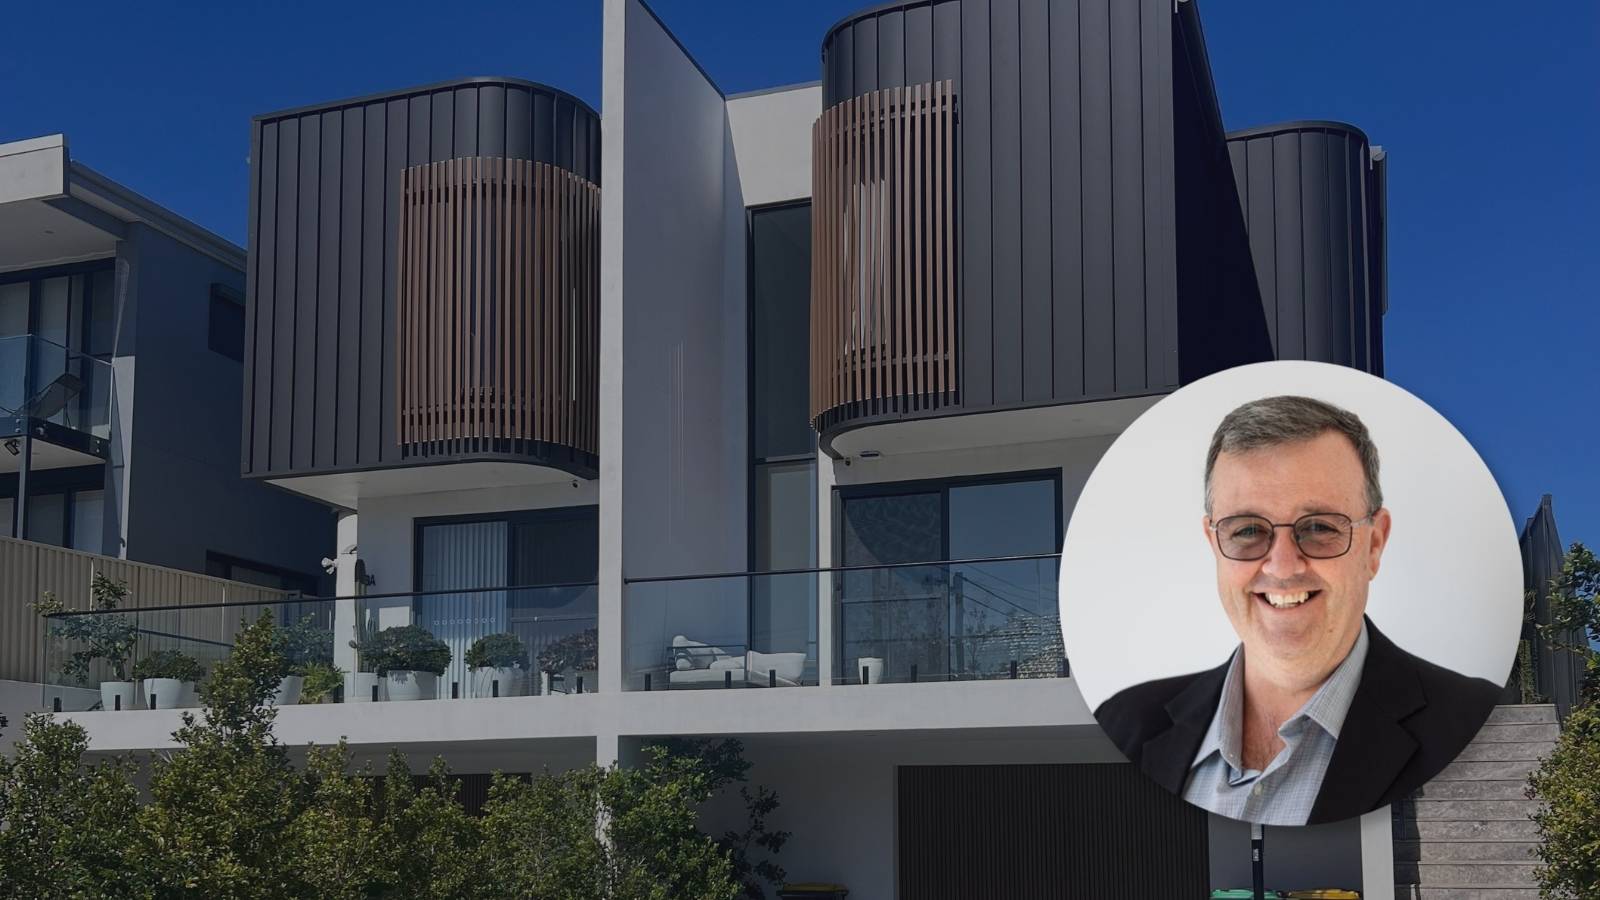
Every year, a mortgage broker walks into a Year 11 and Year 12 classroom at Surf Coast Secondary College and does something most adults avoid: he talks about money, in detail, with teenagers.
Financial literacy is not something that should be taught once at school and then filed away. It stays relevant at almost every age, because understanding where money goes, how financial products work and whether the systems around it are helping or hindering never really stops mattering.
For UFinancial mortgage broker and Torquay director, Paul Nelson, much of that starts with a simple idea: talk about money more often.
That is the thinking behind his financial education sessions at Surf Coast Secondary College, as recently reported by James Taylor. For about 5 years Paul has been visiting the college to cover the topics that rarely make it into a school syllabus but shape almost every adult decision that follows it: bank accounts, budgeting, credit cards, personal loans, compound interest, taxation, payslips and superannuation.
Financial literacy: best developed now, not later
Financial education often gets tied to milestones: buying a first home, taking out a first loan, starting to invest, or approaching retirement. By the time those milestones arrive, your habits are usually already set.
Paul calls it the “dinner table conversation”. The idea that if money comes up naturally and often, young people are more likely to engage with it rather than switch off.
That might mean asking what $10 of pocket money can buy, how long it took to earn, or how household expenses such as electricity, groceries and heating fit into a family budget.
As teenagers begin earning their own income, those conversations naturally expand to saving, interest, tax, super and the responsible use of credit.
There is evidence that the home is already one of Australia’s most important financial classrooms.
In Ecstra Foundation’s 2025 national survey of students, parents and teachers, 80% of students aged 10 to 17 said they learnt about money at home, compared with 65% who reported learning about it at school. Yet only 37% of students said money conversations happened frequently at home. In fact, more than half of parents reported barriers to teaching or talking to their children about money, including a lack of time and gaps in their own knowledge.
For Paul, the quality of the conversation matters as much as having it. Why does one savings account pay more interest than another? What is actually on a payslip, and where does the tax and super go? Small questions like these teach a habit of comparing rather than assuming.
Australia’s cost-of-living environment makes financial literacy more useful
Few of these conversations have felt more urgent than they do right now.
The Australian Bureau of Statistics reported annual CPI inflation of 3.8% in June 2026, with housing costs up 6.8% over the year and food and non-alcoholic beverages up 3.3%. The effect is not identical across every household, but many Australians are earning more than they were a few years ago and still finding less left over once the mortgage, rent, groceries, insurance and utilities are accounted for.
Financial literacy will not shield anyone from the cost-of-living. What it does is make the numbers clearer.
This is one reason budgeting remains a regular part of Paul’s conversations with clients as well as students.
“Budgeting does not mean removing everything enjoyable from your life. It is about understanding what comes in, what goes out and what is being set aside before discretionary spending begins,” said Paul.
For borrowers, that understanding can also be useful when thinking about a home loan. A UFinancial mortgage broker can help clients understand lending options, repayment structures and features such as offset accounts, and discuss how those choices interact with the client’s broader cash-flow position. The right structure will depend on individual circumstances, so the starting point should be understanding the numbers rather than copying somebody else’s system.
Great financial conversations need great information
Paul is careful to draw a line between a financial prediction and an evidence-backed discussion
He argues a stronger financial conversation asks different questions.
- What do we actually know?
- What information is current?
- Where has it come from?
- What could change the outcome?
- And how does any of it affect the decision in front of us?
Those questions have become more important as younger Australians are increasingly getting their financial information online.
ASIC Moneysmart’s 2026 Gen Z research found 72% of Australians aged 18 to 28 used digital and social sources for financial information or guidance, including 63% who used social media. At the same time, respondents ranked source credibility as the most important factor when deciding which information to use.
There is nothing inherently wrong with learning this way. The skill is telling useful information apart from confident commentary, advertising, or advice that simply does not apply to your circumstances. That, too, is part of financial literacy.
"There is nothing inherently wrong with learning this way. The skill is telling useful information apart from confident commentary, advertising, or advice that simply does not apply to your circumstances."
Small decisions can make money work harder
One of the most practical outcomes from Paul’s school sessions has come down to something as ordinary as a savings account.
Former students have told him they compared their banking arrangements and moved their savings once they realised they could earn a better rate. One student, Paul recalls, moved from around 1.5% interest to around 5%.
The important message is that the student checked. They compared. They discussed it with their parents. Then they made an informed choice.
This thinking is not only relevant for young people.
Someone in their 40s or 50s might discover that years of income and expenses are flowing through one transaction account with no real separation between bills, savings and everyday spending.
Another household may have several accounts but no clear idea what any of them are for.
Others are sitting on a mortgage structure nobody has looked at in years.
Paul often talks to clients about separating accounts by purpose and automating regular transfers, so bills, savings and spending are easier to see at a glance. A good system should reduce the amount of mental bookkeeping required each week.
Teaching a teenager how interest works before their first credit card or personal loan is an obvious win. But financial education is not a subject people either learnt at school or missed forever. Adults keep meeting new financial questions their whole lives, and nobody arrives with perfect knowledge of all of them
Teaching a teenager how interest works before their first credit card or personal loan is an obvious win. But financial education is not a subject people either learnt at school or missed forever. Adults keep meeting new financial questions their whole lives, and nobody arrives with perfect knowledge of all of them.
"Adults encounter new financial questions throughout life. Nobody starts with perfect knowledge across all of them."
A local contribution with a wider lesson
Paul’s sessions at Surf Coast Secondary College are a practical example of why community support is so important. Students bring questions, Paul brings experience from years of talking with borrowers about money, and the classroom gives them space to work through topics they will meet again long after they have left it.
The fact that former students still approach him years later to talk about changes they made is perhaps the clearest measure of the value.
But Paul wants to share his message beyond one Surf Coast secondary school classroom.
If more families are comfortable talking about savings at dinner, if more teenagers understand what appears on their payslip, and if more adults question whether their accounts and debts are structured in a way that makes sense for them, financial literacy becomes part of everyday decision-making.
We all work hard for our money. Understanding where it goes, what it costs us and what we are asking it to do is a reasonable place to start.
If you would like to better understand your home loan, lending structure or how your mortgage accounts work together, contact UFinancial to talk it through with a mortgage broker. The aim is not to make money more complicated. It is to give you clearer information for the decisions that matter to you.
This article contains general information only and does not consider your personal objectives, financial situation or needs. Rates, product features and financial conditions can change. Consider seeking appropriate professional advice before making financial decisions.
If you’d like to talk through your lending position after reading this, speak with one of our UFinancial team.